Solar Loan Refinancing: When and How to Lower Payments
Solar loan refinancing can cut your monthly payment. Call (833)-793-7166 to explore options and lower your solar costs today.
By Nathan Russell
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
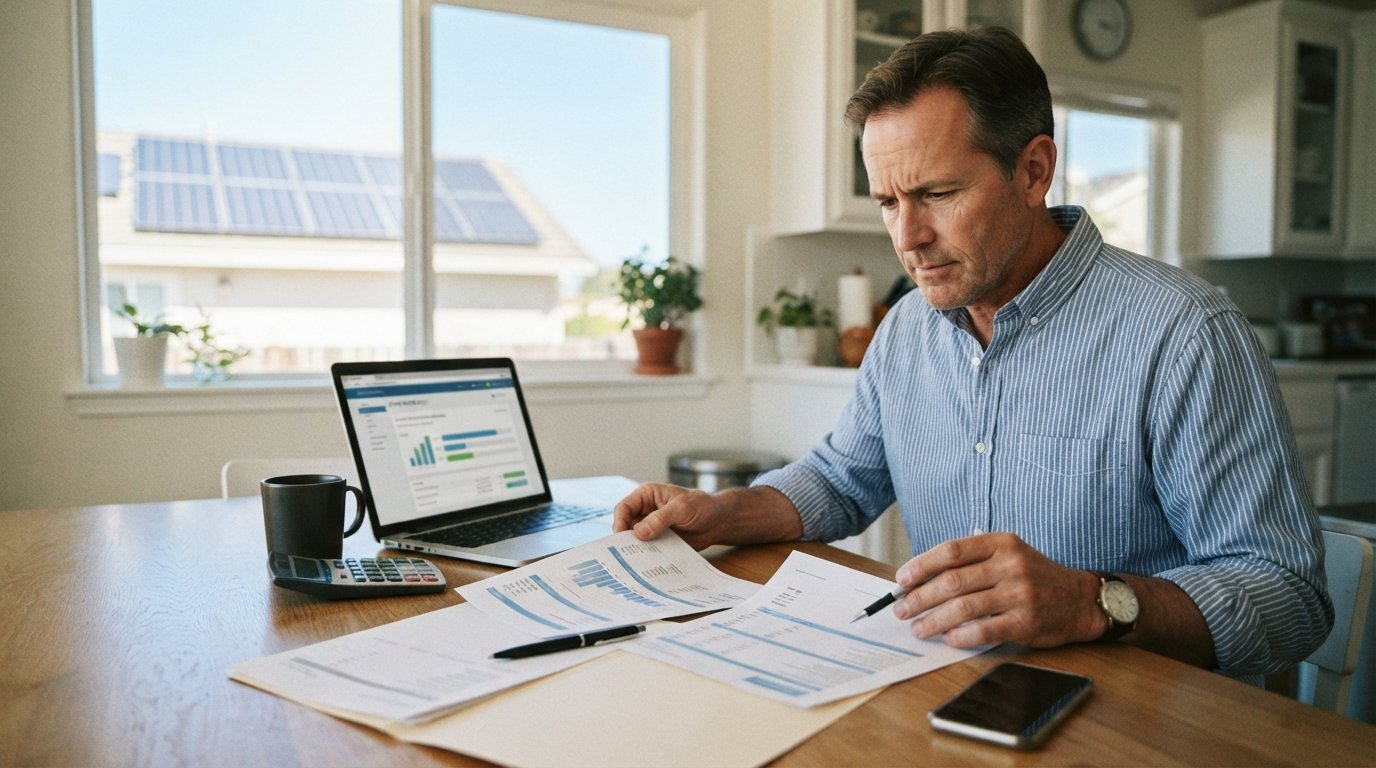
Your solar panels are producing clean energy, but your monthly loan payment may still feel like a burden. If you financed your system a few years ago, you might be paying a higher interest rate than necessary, or your credit score has improved since then. Solar loan refinancing when and how to lower payments is a question many homeowners face after the initial excitement of going solar wears off. The good news is that refinancing can reduce your monthly obligation, but it is not always the right move. This guide walks you through the mechanics, the warning signs, the math, and the risks so you can decide with confidence.
How Solar Loan Refinancing Works and Who Offers It
Refinancing a solar loan means replacing your existing loan with a new one that has different terms, typically a lower interest rate, a longer repayment period, or both. The new lender pays off the old loan, and you make payments to the new lender. In many cases, you can also refinance through a home equity loan or a cash-out refinance of your primary mortgage, but those options come with their own trade-offs. Dedicated solar lenders, credit unions, and online banks are the most common sources for a straight solar loan refinance.
Which lenders actually offer solar loan refinancing? You will not find a dedicated "solar refinance" product at every bank. Instead, you have three main paths. First, some solar-specific financing companies (like those that originally funded your system) may offer a modification or a new loan. Second, credit unions and community banks often have unsecured personal loans or secured loans that can be used to pay off solar debt. Third, you can use a home equity line of credit (HELOC) or a home equity loan, which uses your house as collateral and often provides the lowest rates. Each option has different eligibility requirements, fees, and repayment terms.
Before you apply, gather your current loan documents. You need to know your outstanding principal balance, your current interest rate, your remaining term, and whether there is a prepayment penalty. Most solar loans do not have prepayment penalties, but it is worth verifying. Also check your credit score, since it determines the rate you will be offered. A difference of even one percentage point can save thousands over the life of the loan.
Signs It May Be Time to Refinance Your Solar Loan in 2026
Not every solar loan needs refinancing. But several situations make it a smart move. If interest rates have dropped since you originally financed, or if your credit score has risen by 50 points or more, you are likely paying more than you need to. Similarly, if you chose a short loan term (say, 5 or 7 years) and the payment is straining your monthly budget, stretching the term could free up cash flow, though you will pay more interest overall. Another sign: you have paid down a significant portion of the principal and want to reduce the remaining interest cost.
Here are the most common triggers that justify a closer look at refinancing:
- Your current interest rate is at least 1% higher than today's average for a similar loan.
- Your credit score has improved substantially since you first financed the system.
- You need to lower your monthly payment to afford other financial goals (emergency fund, home repairs, etc.).
- You are considering selling your home and want to make the solar loan more attractive to buyers.
One more sign: you have an adjustable-rate solar loan that is about to reset. If your rate is set to increase, refinancing into a fixed-rate loan can protect you from future payment shocks. In 2026, with many homeowners watching rate trends, a fixed-rate refinance offers predictability that variable rates cannot match.
The Impact of Dealer Fees and Origination Charges on Refinance Math
When you refinance, you are not just comparing interest rates. You must also account for the fees that come with the new loan. Dealer fees (sometimes called origination fees or lender fees) can range from 1% to 5% of the loan amount. On a $20,000 solar loan, a 3% fee adds $600 to your balance or requires cash upfront. That fee can wipe out the savings from a slightly lower interest rate if you are not careful. Always ask for a Loan Estimate that lists every fee, including application fees, appraisal fees (if any), and prepaid interest.
To run the math correctly, compare the total cost of the new loan (principal + fees + interest over the life of the loan) against the total remaining cost of your current loan. If the new loan's total cost is lower, refinancing saves you money. If the fees are high and the term is long, you might end up paying more even with a lower rate. For example, refinancing a $15,000 balance from 9% to 6% over 10 years saves about $3,000 in interest. But if the new loan carries a $900 origination fee, your net savings drop to $2,100. Still worthwhile, but you need to know the real numbers.
Also watch for prepayment penalties on your existing loan. Though rare in solar financing, some lenders charge a fee if you pay off the loan early. That fee must be added to your refinance cost. Finally, if you roll the fees into the new loan, you are financing them, which means you pay interest on them. It is often better to pay fees out of pocket if you can.
Risks of Extending the Loan Term and Resetting the Payback Clock
The most tempting way to lower your monthly payment is to stretch the loan term. Going from a 10-year loan to a 20-year loan can cut your payment nearly in half. But that lower payment comes with a hidden cost: you pay interest for many more years, and you may end up paying far more overall. Worse, you reset the payback clock on your solar investment. Solar payback period is the time it takes for your energy savings to equal your system cost. If you refinance and extend the term, you delay the point at which you truly break even. For a deeper dive into how payback works, see our guide on solar payback calculation: when will you save.
Another risk: you might still owe more than the solar system adds to your home's value when you sell. Solar adds value, but not always dollar-for-dollar. If you extend the loan to 25 years, you could be upside-down on the loan for a long time. That makes selling harder because you would need to bring cash to closing. Lenders and buyers may also be wary of assuming a solar loan with a long remaining term.
Finally, consider the psychology of a lower payment. It feels good, but it can mask the fact that you are not building equity as quickly. If your goal is to own your system free and clear as soon as possible, a longer term works against you. Weigh the monthly relief against the total cost and your long-term plans.
How to Lower Your Solar Payments Without Refinancing
Refinancing is not the only lever. Sometimes you can reduce your payment by renegotiating with your current lender. Some lenders offer a rate reduction or a term extension for a small fee. It costs nothing to call and ask. You can also make a lump-sum principal payment if you have savings, which lowers the remaining balance and may allow you to recast the loan (re-amortize it) to a lower payment. Not all lenders allow recasting, but it is worth asking.
Another option: if your solar loan is unsecured, you might qualify for a 0% APR balance transfer credit card, but that is risky because credit limits are usually too low and the promotional period is short. A better route for some is a home equity loan or HELOC, which often has lower rates than unsecured solar loans. Just remember that your home is collateral, so you risk foreclosure if you default. For homeowners who are also planning a move, resources like Moving.Homes offer checklists and guides that can help you manage the logistics of selling a home with solar, including how to transfer or pay off a loan.
If you are struggling with payments, contact your lender immediately. Many have hardship programs that can temporarily reduce or pause payments. Ignoring the problem leads to late fees and credit damage. It is always better to ask for help early.
Step-by-Step: How to Refinance Your Solar Loan
If you have decided that refinancing makes sense, follow a structured process to avoid mistakes. Start by checking your credit report for errors and disputing any inaccuracies. Then gather quotes from at least three lenders, including your current lender, a credit union, and an online lender. Compare not just rates but also fees, terms, and whether the loan is secured or unsecured.
Here is a practical sequence to follow:
- Pull your credit reports and scores for free from AnnualCreditReport.com.
- Request loan estimates from multiple lenders within a 14-day window to minimize credit score impact.
- Compare the APR (annual percentage rate), not just the interest rate, because APR includes fees.
- Choose the best offer and submit a formal application.
- Once approved, the new lender pays off your old loan, and you begin making payments to the new lender.
After you close, set up autopay to avoid missed payments and consider making extra principal payments when possible. Even $50 extra per month can shorten your loan term significantly. Also, keep your loan documents in a safe place; you may need them for taxes if you claim the solar tax credit, though the credit is typically taken in the year the system was installed. Refinancing does not create a new tax credit.
Alternatives to Refinancing: When to Walk Away
Refinancing is not always the answer. If your current rate is already low (say, 3% or 4%), refinancing to a slightly lower rate may not be worth the fees and hassle. If you plan to sell your home within a year or two, the closing costs will not have time to pay for themselves. And if your credit score has dropped, you may not qualify for a better rate anyway. In those cases, focus on making extra payments or simply keeping your current loan.
Also consider whether your solar loan is truly a burden or just a mental block. If you are saving more on electricity than you pay on the loan, you are already cash-flow positive. Refinancing might reduce your payment further, but it also extends your debt. Sometimes the best move is to stay the course. Run the numbers with a spreadsheet or an online calculator, and trust the math over the emotional appeal of a lower monthly bill.
Before you sign anything, read the fine print. Look for prepayment penalties, balloon payments, and variable rates. A loan that starts low but adjusts upward can hurt you later. Fixed-rate loans are generally safer for long-term planning. If you are unsure, consult a nonprofit credit counselor or a HUD-approved housing counselor. They can review your situation for free or low cost.
Solar loan refinancing when and how to lower payments ultimately comes down to your goals. If you want lower monthly payments and can accept a longer term, refinancing can work. If you want to minimize total interest and own your system sooner, a shorter term or extra payments may be better. Whichever path you choose, get multiple quotes, do the math, and never rush. Your solar investment should save you money, not add stress.