Commercial Solar PPA Cash Flow Modeling Guide
Model commercial solar PPA cash flow with confidence. Call (833)-793-7166 for expert guidance on escalators, savings, and contract terms.
By Thomas Hayes
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
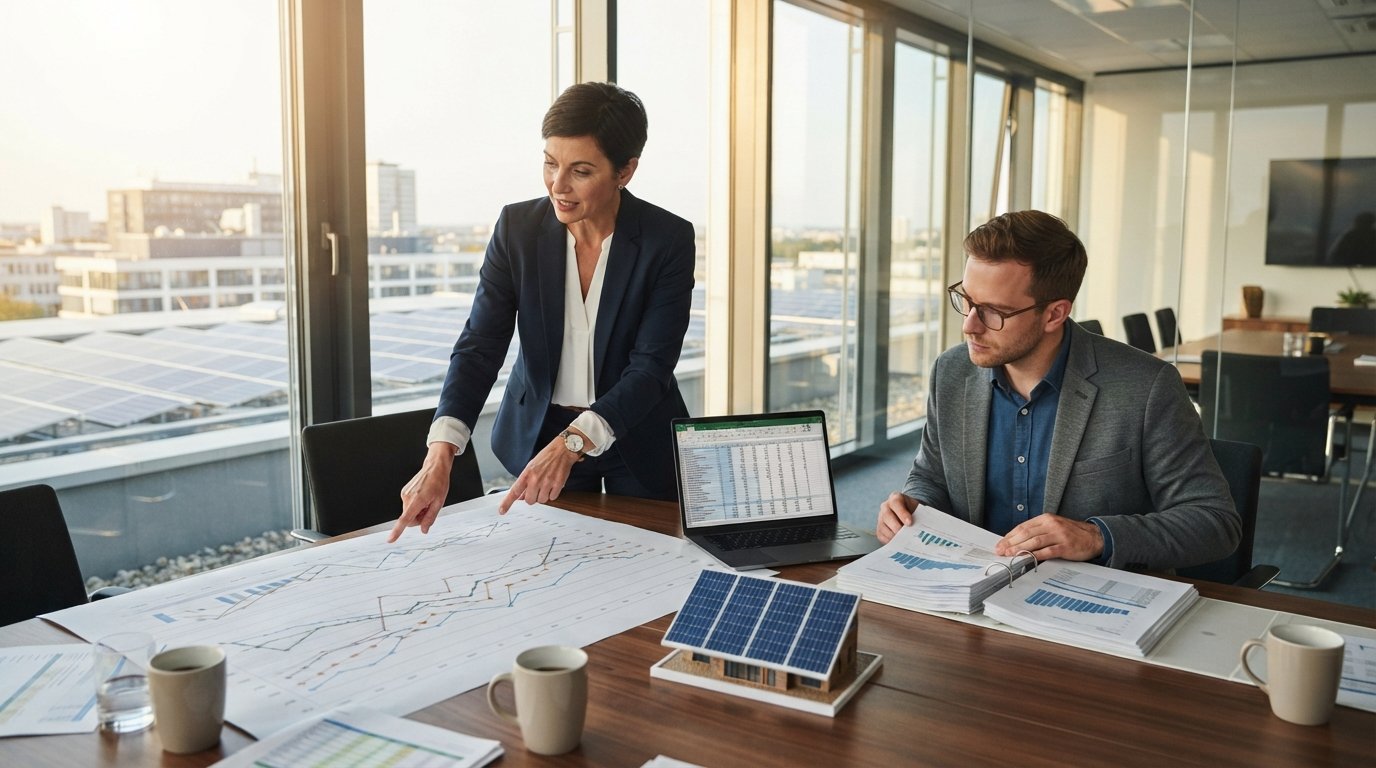
Commercial solar power purchase agreement cash flow modeling is the financial bridge between a promising clean energy idea and a board-ready decision. For CFOs and small business owners, a solar PPA is not simply an environmental gesture; it is a long-term operating contract that reshapes monthly expenses, balance sheet treatment, and end-of-term optionality. Without a disciplined model, it is easy to overstate savings, understate escalators, or miss the interaction between third-party incentives and your own tax position. This guide walks through the core mechanics, the assumptions that matter most, and the scenario techniques that turn a PPA proposal into a defensible cash flow forecast.
Why Commercial Solar PPA Cash Flow Modeling Matters
A commercial solar power purchase agreement allows a third-party provider to own, install, and maintain a solar array on your property while your business buys the electricity at a contractually fixed rate. That structure converts a large capital expense into a predictable operating cost, but predictability is not the same as simplicity. The provider sets a PPA rate, often with an annual escalator, and you compare that rate against what you would otherwise pay the utility. The entire value proposition rests on the spread between those two numbers over 15 to 25 years. If your model uses a single average utility rate and ignores escalation, the projected savings can look far better than reality.
Cash flow modeling for a PPA must capture timing, not just totals. Utility bills arrive monthly, PPA payments arrive monthly, and annual true-ups or demand charges can swing a single month dramatically. A model that only shows annual savings hides the months when cash flow is tight. For a business with seasonal revenue, that timing mismatch can matter more than the headline savings figure. The goal is a month-by-month forecast that reflects how the contract actually bills, then rolls up into annual and lifetime views for executive review.
Before building any spreadsheet, gather the baseline data that anchors the model. You need 12 to 36 months of utility bills with usage, demand, and total cost broken out; the proposed PPA rate, escalator, and term; the estimated production profile for your location and roof or ground mount; and your business's tax status and financing constraints. If you are still evaluating system size and upfront costs, our guide to commercial solar installation costs for small business provides a useful benchmark before you model the PPA alternative.
Modeling PPA Rate Escalators Against Utility Rate Escalation
The single most consequential assumption in any commercial solar PPA cash flow model is the relationship between the PPA escalator and the utility rate escalation. Most PPAs include a fixed annual escalator, commonly in the 1.5% to 3.5% range, applied to the PPA rate each year. Utility rates, by contrast, are not contractually fixed. They have historically risen at varying rates depending on region, fuel costs, infrastructure investment, and regulatory decisions. Your model must treat these as two separate curves and test how sensitive the savings are to the gap between them.
A common mistake is to assume the PPA rate stays flat while the utility rate rises, which flatters the economics. In practice, a PPA with a 2.5% escalator and a utility rate rising at 2.5% produces flat savings in real terms, not growing savings. The model should explicitly show the year in which the PPA rate crosses the utility rate under different utility escalation scenarios. For many contracts, the early years deliver strong savings, and the later years narrow or even reverse if utility rates stagnate. Knowing that crossover year is essential for negotiating contract terms and for setting expectations with stakeholders.
Build at least three utility escalation scenarios into your model: a low case (1% to 2%), a base case (2.5% to 3.5%), and a high case (4% or more). Pair each with the contractual PPA escalator and calculate annual and cumulative savings. The output should be a table that shows, for each scenario, the first-year savings, the year savings peak, and the year cumulative savings turn positive after any upfront costs. This exercise also reveals whether the PPA's escalator is competitive; a 3.5% escalator in a region with historically modest utility increases may be a poor deal even if the first-year rate looks attractive.
- Low utility escalation: tests whether the PPA still saves money if rate increases slow.
- Base utility escalation: aligns with regional historical averages and utility filings.
- High utility escalation: captures upside but should not be the only case presented.
- Contractual PPA escalator: fixed, so it should be applied exactly as written, including any step-ups.
Document the source of each utility escalation assumption. Public utility commission filings, regional rate forecasts, and your own historical bill data are all defensible. Avoid using a single national average, because commercial electricity rates vary widely by state and utility. The model is only as credible as its assumptions, and a CFO reviewing the forecast will want to see where each number came from.
How PPA Payments Appear on Financial Statements
Accounting treatment is where cash flow modeling and financial reporting intersect, and the distinction between an owned system and a PPA is significant. With an owned system, the business capitalizes the asset, depreciates it, and may claim federal incentives directly. With a commercial solar PPA, the provider owns the system and claims the federal Investment Tax Credit and depreciation benefits. Your business simply records the monthly PPA payment as an operating expense, typically under utilities or energy costs. That keeps the obligation off the balance sheet as debt, which can be attractive for businesses managing leverage ratios or loan covenants.
However, off-balance-sheet does not mean off the radar. Lenders and investors increasingly scrutinize long-term energy contracts as fixed obligations, and a 20-year PPA can be treated similarly to a lease in credit analysis. Your cash flow model should therefore include a schedule of total fixed PPA payments by year, alongside a comparison to the variable utility costs they displace. This lets finance teams show both the income statement effect (lower and more predictable energy expense) and the cash flow effect (avoided utility outflows minus PPA outflows). It also helps explain why the PPA may improve budget certainty even if the net savings in a given year are modest.
For tax purposes, because the third-party provider claims the federal incentives, your business does not need to navigate the Investment Tax Credit or depreciation schedules for the solar asset. That simplifies tax planning but also means the PPA rate already reflects the provider's incentive economics. When comparing a PPA to a cash purchase or loan, the model should adjust for this: an owned system may deliver a lower levelized cost of energy precisely because the business captures the tax benefits. The comparison is not apples to apples unless the model accounts for who claims what.
If your business is planning a relocation or facility change during the contract term, the assignment and transfer provisions of the PPA become part of the financial model. Early termination fees, buyout formulas, and assignment consent requirements can create material cash outflows. For broader context on managing a move, resources such as Moving.Homes relocation guides can help teams plan the logistics, but the PPA model should separately quantify the financial exposure of exiting or assigning the contract early.
End-of-Term Purchase Options and Renewal Terms
Most commercial solar PPAs run 15 to 25 years, and the end-of-term provisions deserve their own line items in the cash flow model. Common structures include a fair market value purchase option, a fixed buyout price, and renewal at a reduced rate. Each option produces a different terminal cash flow, and the model should present them side by side rather than assuming the business walks away. A fixed buyout that looks expensive in year 20 may be attractive if utility rates have risen sharply and the system still has 10 to 15 years of productive life.
Renewal terms are often the least modeled and most negotiated element. Some contracts automatically renew at a specified percentage of the original rate, while others revert to fair market value or require renegotiation. If the renewal rate is favorable, the post-term savings can be substantial and should be included in the lifetime analysis. If it is unfavorable, the business may face a choice between buying the system, renewing at a higher rate, or removing the equipment. Model all three paths and assign rough probabilities based on the contract language and market conditions.
- Estimate the system's residual value at the end of the initial term using degradation, remaining incentives, and market comparables.
- Compare that value to the stated purchase option price to determine whether exercise is economically rational.
- Model renewal payments at the contractual or projected rate and compare them to projected utility costs at that time.
- Include removal and site restoration costs as a downside scenario if none of the options are attractive.
The end-of-term analysis also informs the upfront negotiation. If the purchase option formula is vague, ask for a specific schedule. If renewal is at fair market value, request a cap or a defined appraisal process. These details are easy to overlook during the excitement of signing, but they can swing the lifetime net present value by a meaningful margin.
Interaction With Federal Incentives Claimed by the PPA Provider
Under a commercial solar PPA, the third-party owner is typically eligible to claim the federal Investment Tax Credit and accelerated depreciation, and those benefits are embedded in the PPA rate you are offered. The provider is not passing the credit to you directly; it is using the credit to lower its own capital cost and, in theory, to offer a more competitive rate. Your cash flow model should not add the Investment Tax Credit as a benefit to your business, because you are not claiming it. Doing so is one of the most common modeling errors and can overstate returns by 20% to 30%.
What the model should do is stress-test whether the PPA rate reflects a reasonable share of those incentives. If you have received competing proposals, compare the PPA rates against the prevailing market and against the economics of an owned system where you would claim the credit. For businesses with sufficient tax appetite, ownership often produces a lower levelized cost because the incentives accrue directly. The PPA's advantage is simplicity and zero upfront capital, not necessarily the lowest lifetime cost. Presenting both paths in the model gives decision-makers a clear trade-off between capital efficiency and total savings.
Also account for any state or utility incentives that may flow to the host rather than the system owner. Some programs, such as certain renewable energy credit markets or state rebates, may be assignable or may accrue to the host depending on contract terms. Read the PPA carefully to determine who owns environmental attributes and whether any host-level incentives exist. If they do, add them as separate cash flow lines with their own eligibility assumptions and expiration dates.
Scenario Modeling Tips for CFOs and Small Business Owners
Effective commercial solar power purchase agreement cash flow modeling is less about a single perfect forecast and more about a range of credible outcomes. CFOs should insist on a scenario framework that includes base, upside, and downside cases, each with clearly documented assumptions. Small business owners, who may not have a dedicated finance team, can use a simplified version of the same framework to avoid being surprised by escalators or end-of-term costs. The following practices make the model more useful and more defensible.
- Build monthly, report annually: monthly detail captures billing timing and seasonal load, while annual rollups keep the executive summary readable.
- Separate fixed and variable costs: PPA payments are largely fixed per kWh, while utility bills include demand charges and riders that may not disappear.
- Include a sensitivity table: show net present value across combinations of utility escalation and PPA escalator so decision-makers see the range, not a point estimate.
- Document every assumption: source, date, and rationale for each input, so the model can be audited or updated as rates change.
- Model the exit: include early termination, assignment, and end-of-term options as explicit scenarios rather than footnotes.
Finally, validate the model against actual results after the first year of operation. Compare projected production and savings to actual utility bills and PPA invoices. Variances are normal, but they reveal whether the original assumptions were optimistic. Updating the model annually with real data keeps the forecast honest and improves future decision-making, whether you are renewing a contract, adding storage, or evaluating a second site. A model is a living tool, not a one-time exercise, and the businesses that treat it that way get the most value from their solar investment.
Commercial solar power purchase agreement cash flow modeling ultimately answers a simple question: does this contract improve the financial trajectory of the business under a realistic range of futures? By separating PPA and utility escalation curves, respecting accounting treatment, planning for end-of-term options, and correctly handling third-party incentives, finance teams can turn a complex proposal into a clear, defensible decision. Start with clean utility data, build the monthly model, test the scenarios, and let the numbers, not the sales pitch, drive the choice.