Commercial Solar Case Study: Small Business Savings Example
Follow a 150 kW commercial solar case study small business savings example, from load profile to payback. Call (833)-793-7166 for expert guidance.
By Brandon Moore
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
When a small business owner looks at a commercial solar proposal, the first question is rarely about panel brands or inverter efficiency. It is almost always about the money: what will this cost, what will it save, and when does the break-even point arrive? A realistic commercial solar case study answers those questions with numbers, not marketing language. This walkthrough follows a fictional but representative small business through the full process, from load profile analysis to financing structure, incentive stacking, and long-term operations. The goal is to show how a commercial solar case study small business savings example actually works in practice, so you can benchmark your own project against a concrete scenario.
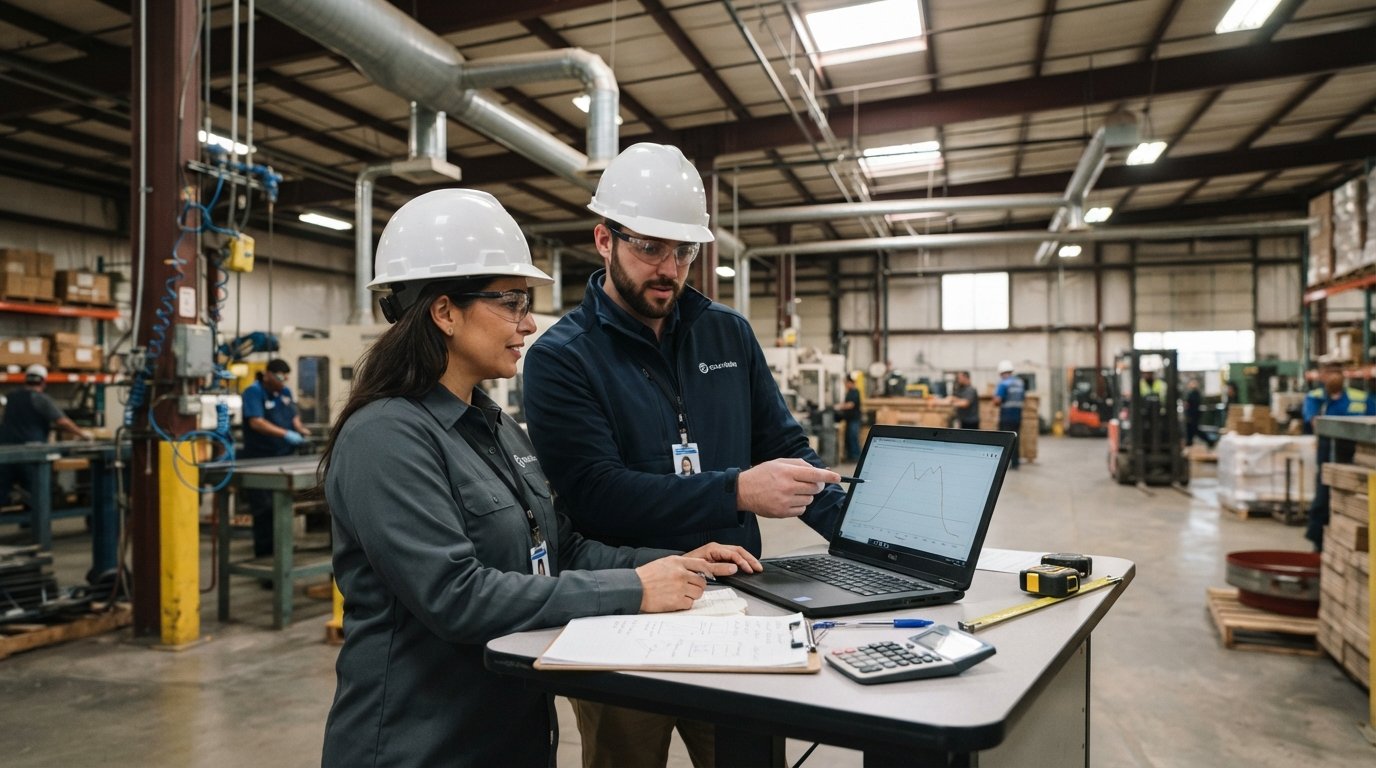
The example business is a 12,000 square foot light manufacturing and distribution facility in Central Texas. It runs one daytime shift, uses significant HVAC and compressed air loads, and pays a commercial electricity rate of roughly 11 cents per kWh. Its annual consumption is about 240,000 kWh, and its average demand is around 55 kW with peaks near 90 kW. Those figures matter because commercial solar sizing is driven by load shape, not just roof area. Before any savings projection is credible, the installer must understand when and how the business uses power.
Load Profile and Roof Assessment: The Foundation of Every Savings Estimate
The first step in any credible commercial solar case study is a load profile review. A solar array produces power on a curve that peaks at midday, so a business that runs heavy loads during daylight hours will self-consume a much higher share of its solar generation than a business that operates primarily at night. For the example facility, roughly 70 percent of annual consumption occurs between 7 a.m. and 6 p.m., Monday through Friday. That is a favorable profile for solar because it aligns generation with demand, reducing the amount of power exported to the grid at low net-metering rates.
To build the load profile, the installer pulled 12 months of utility interval data and identified base load, peak demand windows, and seasonal variation. Summer months showed the highest consumption due to cooling loads, which also happen to coincide with the strongest solar production. This seasonal alignment improves the economics further. The installer then performed a roof assessment covering structural capacity, shading, membrane condition, and available clear area. The building had a flat TPO roof with about 8,000 square feet of usable space, no significant shading from adjacent structures, and structural capacity to support a ballasted racking system without penetration.
Based on the load profile and roof capacity, the installer proposed a 150 kW DC system using 400-watt modules and string inverters. The estimated first-year production was approximately 210,000 kWh, or about 87 percent of annual consumption. That ratio is intentional: oversizing beyond annual consumption rarely pays back at commercial net-metering rates, and undersizing leaves savings on the table. The system was designed to maximize self-consumption during the workday, with the remainder credited through the utility's commercial net-metering program.
Several practical checks rounded out the assessment before financial modeling began. The installer verified interconnection capacity with the local utility, reviewed the utility's commercial net-metering tariff, and confirmed that the roof had at least 15 years of useful life remaining. They also checked the business's insurance policy for any solar-related endorsement requirements. These steps are not glamorous, but they prevent costly surprises later. For a deeper look at how these cost components add up, see this guide to commercial solar panel installation costs for small businesses, which breaks down equipment, labor, and permitting line items.
Financing Structure: How Cash Flow and Tax Treatment Change the Outcome
The same 150 kW system can produce very different financial results depending on how it is financed. The example business evaluated three options: a cash purchase, a commercial solar loan, and a power purchase agreement (PPA). Each structure changes upfront cash flow, ongoing payments, ownership of tax benefits, and the total cost of energy over time. Presenting all three in the case study makes the trade-offs concrete.
Under a cash purchase, the business pays the full installed cost of approximately $375,000 (roughly $2.50 per watt before incentives) and owns the system outright. It captures the 30 percent federal Investment Tax Credit (ITC), which in 2026 is available for commercial projects, plus accelerated depreciation through MACRS and bonus depreciation rules. The business also receives all utility bill savings and any renewable energy certificate (REC) revenue. The trade-off is the large capital outlay and the fact that the business bears maintenance responsibility.
Under a commercial solar loan, the business might put 10 percent down and finance the remainder over 10 to 15 years at a fixed rate. The loan payment is often structured to be lower than the monthly utility bill savings in the first year, creating positive cash flow from day one. The business still owns the system and captures the ITC and depreciation, which can be used to pay down the loan faster. This structure is attractive for businesses that want ownership benefits without draining cash reserves.
Under a PPA, a third-party owner installs and owns the system, and the business buys the solar electricity at a fixed rate below its utility rate, often with an escalator. The business avoids upfront cost and maintenance responsibility but does not capture the ITC or depreciation directly; those benefits flow to the PPA provider and are reflected in the PPA rate. The PPA can be a good fit for businesses with limited tax appetite or capital constraints, but it typically delivers lower lifetime savings than ownership.
The table below summarizes the first-year financial picture for each option, using conservative assumptions and noting that actual results vary by location, utility, and tax situation.
- Cash purchase: $375,000 upfront, $112,500 ITC, first-year utility savings of about $23,000, plus depreciation tax benefits.
- Commercial loan: $37,500 down, monthly loan payment near $2,600, first-year savings of about $23,000, positive cash flow in year one.
- PPA: $0 upfront, PPA rate of about $0.09 per kWh versus $0.11 utility rate, first-year savings of about $4,000 to $6,000.
The comparison shows why financing structure matters as much as system size. A business that can use the tax credits and depreciation will usually find ownership (cash or loan) more lucrative over the system's 25-year life. A business that cannot use the credits efficiently may prefer a PPA despite lower savings. The case study approach forces the owner to confront these trade-offs with numbers rather than assumptions.
Depreciation and Incentive Stacking in a Business Scenario
Commercial solar economics differ from residential economics primarily because of depreciation. A business can depreciate the solar system using the Modified Accelerated Cost Recovery System (MACRS) over five years, and in many cases can combine that with bonus depreciation. The 30 percent ITC reduces the depreciable basis, but the combined effect of the ITC and accelerated depreciation can cover a substantial share of the system cost in the early years.
In the example, the $375,000 system generates a $112,500 ITC, leaving a depreciable basis of $262,500. Using five-year MACRS with bonus depreciation assumptions, the business could deduct a large portion of that basis in the first year, producing a tax shield that depends on the business's effective tax rate. For a business in the 21 percent federal corporate tax bracket, the depreciation tax shield could be worth roughly $55,000 in present value terms, though the exact figure depends on the business's tax position and whether state depreciation conforms to federal rules.
Beyond federal incentives, the business may be eligible for state or local programs. Texas, for example, offers a property tax exemption for solar installations, which protects the business from an increased assessed value attributable to the system. Some utilities offer commercial solar rebates or performance-based incentives, and REC markets can provide modest additional revenue. The case study should list every applicable incentive and note that programs change, so verification with current official sources is essential before finalizing a financial model.
Stacking these incentives changes the payback math dramatically. On a cash purchase, the simple payback period without incentives might be around 16 years. With the ITC, depreciation, and utility savings, the simple payback drops to roughly 6 to 7 years, and the 25-year net present value becomes strongly positive. The internal rate of return (IRR) for the cash purchase in this example lands in the low-to-mid teens, which is competitive with many small business investment alternatives. For the loan scenario, the IRR on the down payment can be even higher because the business is leveraging the tax benefits against a relatively small equity outlay.
It is worth noting that incentive stacking is not automatic. The business must have sufficient tax liability to use the ITC and depreciation, must comply with prevailing wage and apprenticeship requirements for the full ITC rate, and must document everything carefully. A tax advisor should review the model before the business commits. The case study should present these as planning requirements, not footnotes.
Operations and Maintenance: The Long-Term View
Commercial solar systems are long-lived assets, and the case study is incomplete without a realistic operations and maintenance (O&M) plan. The example system carries a 25-year performance warranty on modules and a 10-to-12-year warranty on inverters, but warranties do not cover everything. The business should budget for annual O&M costs, typically 1 to 2 percent of the original installed cost, or about $3,750 to $7,500 per year in this case. That budget covers periodic cleaning (especially in dusty regions), inverter monitoring, electrical inspections, and occasional component replacement.
Inverter replacement is the most significant expected cost over the system life. String inverters typically last 10 to 15 years, so the example business should plan for one inverter replacement around year 12 to 15, costing perhaps $15,000 to $25,000 depending on the model and labor. Microinverter or module-level power electronics architectures change this calculation, but the case study uses string inverters for cost efficiency. Monitoring is included in most O&M contracts and provides early warning of underperformance, which protects savings.
Insurance and roof maintenance also deserve attention. The business should confirm that its property insurance covers the solar system and that any roof warranty remains valid after installation. If the roof needs replacement before the solar system's useful life ends, the cost of removing and reinstalling the array must be factored in. In the example, the roof had enough remaining life to avoid this issue, but many commercial projects require a roof evaluation and sometimes a roof replacement before solar installation. Planning for these contingencies keeps the savings projection honest.
Finally, the case study should track actual performance against the model. Commercial solar systems are typically monitored remotely, and the business should review production data monthly against the estimated production curve. If performance dips, the O&M provider can investigate soiling, shading, or equipment faults before savings erode. This discipline turns a static case study into an ongoing management tool. Businesses that want help comparing installer proposals and O&M terms can use resources like ContractorHomeQuotes to plan renovation and improvement projects with transparent pricing data, which is useful when solar is part of a broader facility upgrade.
Putting the full picture together, the example business sees a first-year utility savings of about $23,000, a federal ITC of $112,500, depreciation benefits worth tens of thousands more, and modest O&M costs that are more than offset by savings. Over 25 years, the cumulative net savings for the cash purchase scenario land in the range of $350,000 to $450,000 depending on utility rate escalation and degradation. The loan scenario produces similar lifetime savings but with lower upfront capital and positive cash flow from year one. The PPA delivers smaller but still meaningful savings with no capital outlay.
What makes this commercial solar case study small business savings example useful is not the specific dollar figures, which will vary by region and utility, but the method. Start with a real load profile, size the system to self-consumption, model multiple financing structures, stack incentives carefully, and budget for O&M. Business owners who follow that sequence can evaluate any commercial solar proposal with confidence and avoid the two most common mistakes: oversizing without regard to load shape and underestimating the value of depreciation and tax credits. If you want to see how your own facility's numbers compare, the next step is a free, no-obligation quote from a vetted commercial solar provider, backed by transparent information and consumer advocacy rather than sales pressure.