Solar Loan Dealer Fees Explained for Homeowners
Solar loan dealer fees can add thousands to your system cost. See how they work and how to avoid paying more than you should.
By Brandon Moore
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
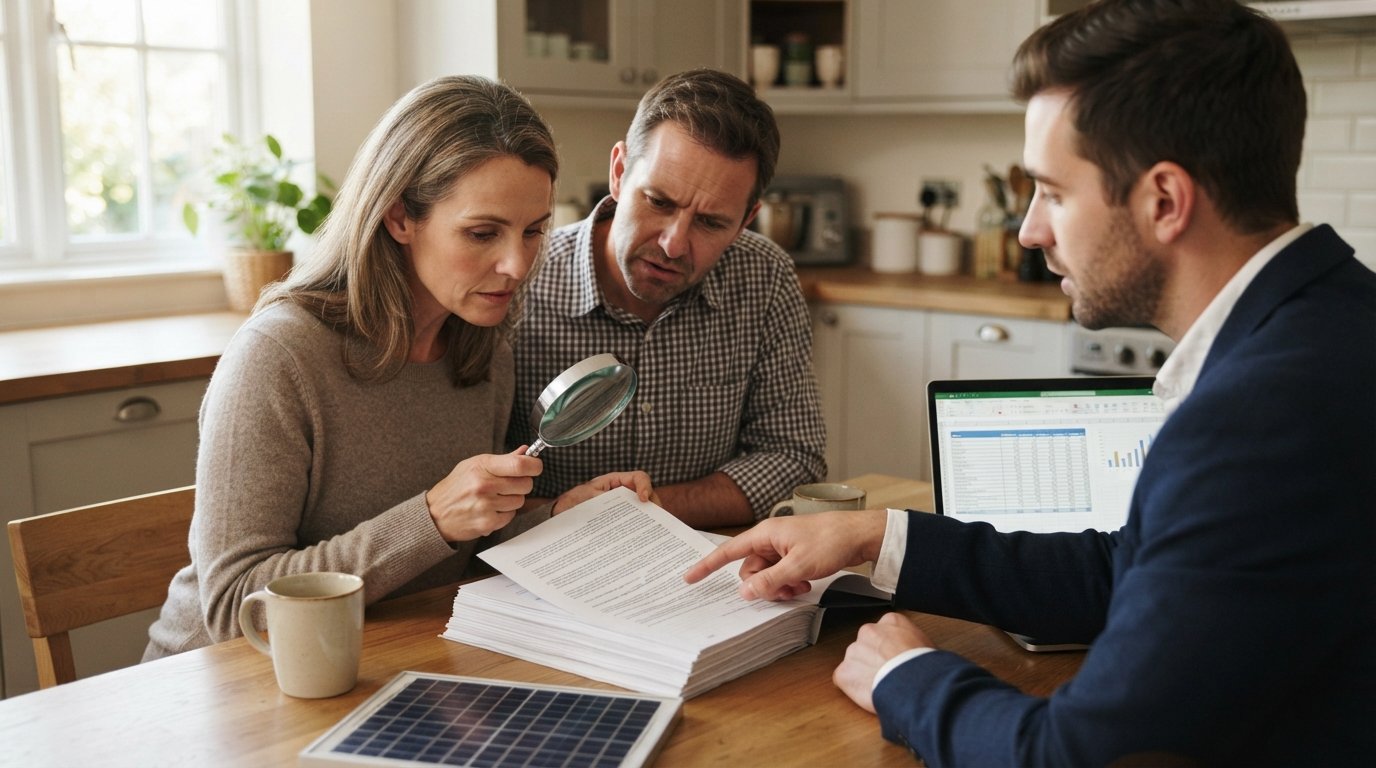
You sit down with a solar salesperson, and the pitch sounds perfect: zero down, low monthly payments, and immediate savings on your electric bill. Then you reach the fine print and spot a line item called a dealer fee, sometimes adding thousands of dollars to your loan balance before a single panel touches your roof. For many homeowners, this is the moment a simple solar purchase turns into a confusing math problem. Understanding what that fee is, why it exists, and how it affects your bottom line is one of the most important steps you can take before signing anything.
What Are Solar Loan Dealer Fees?
A solar loan dealer fee is a charge baked into your financing by the lender, then paid by the solar installer or sales dealer to secure your loan. It is not a fee you write a separate check for. Instead, it is added to your loan principal, which means you pay interest on it for the life of the loan. In practice, the dealer fee is the cost of buying down your interest rate so the monthly payment looks more attractive in the sales presentation.
Here is how the mechanics typically work. The lender offers the installer two options: a loan with a higher interest rate and no dealer fee, or a loan with a lower interest rate and a dealer fee of 15 to 35 percent of the system cost. The installer almost always chooses the second option because a lower advertised rate closes more deals. That fee is then passed to you through a higher total loan amount. You may see a 2.99 percent rate on your contract, but the real cost of borrowing is much higher once the inflated principal is factored in.
The practical effect is easy to miss. A $25,000 solar system with a 25 percent dealer fee becomes a $31,250 loan. You still think you financed $25,000, but you are actually paying interest on $31,250. Over a 25-year term, that extra $6,250 can add several thousand dollars in additional interest. This is why two homeowners with identical systems and identical credit scores can end up with dramatically different total costs.
Why Dealer Fees Exist and Who Pays Them
Dealer fees exist because solar financing is unsecured. Unlike a car loan or a mortgage, there is no asset the lender can easily repossess if you stop paying. Solar panels are bolted to your roof and have limited resale value on their own. To compensate for that risk, lenders charge the dealer a fee upfront, and the dealer passes that cost to you through the loan amount. It is a risk premium disguised as a rate buydown.
The solar sales industry also relies heavily on third-party dealers and lead generation networks. These dealers often pay for leads, commissions, and marketing, and the dealer fee is one of the few places they can recover those costs while still showing a low monthly payment. The result is a system where the advertised rate and the true cost of borrowing are two very different numbers.
Who actually pays the fee? You do, even if it never appears as a separate line item on your invoice. It is embedded in the loan principal, which means it also affects your loan balance, your interest charges, and potentially your ability to pay off the loan early without a prepayment penalty. Some lenders also structure dealer fees as a prepaid finance charge, which can affect the annual percentage rate (APR) disclosed under the Truth in Lending Act. Always compare the APR, not just the interest rate, because the APR captures the dealer fee and other financing costs.
How Dealer Fees Affect Your Total Cost
The single biggest mistake homeowners make is comparing solar quotes by monthly payment alone. A lower monthly payment can hide a much higher total cost. To see the real picture, you need to compare the total amount financed, the APR, and the total interest paid over the life of the loan.
Consider two quotes for the same $25,000 system. Quote A offers a 7.99 percent interest rate with no dealer fee, resulting in a loan of $25,000. Quote B offers a 2.99 percent rate with a 25 percent dealer fee, resulting in a loan of $31,250. Quote B has the lower monthly payment, but over 25 years it can cost $15,000 or more in additional principal and interest. The table below illustrates the difference in simple terms.
- Quote A: $25,000 financed at 7.99 percent, total repaid around $57,000 over 25 years.
- Quote B: $31,250 financed at 2.99 percent, total repaid around $44,000 over 25 years, but with a higher balance and less equity in the system.
- Key takeaway: The lower rate does not always mean the lower total cost, especially if you plan to sell your home or pay off the loan early.
Dealer fees also affect your solar payback period. If you finance $31,250 instead of $25,000, your break-even point moves further into the future. That can turn a seven-year payback into a ten-year payback, which changes the entire financial case for going solar. Homeowners who plan to move within a few years should be especially cautious, because the higher loan balance may exceed the added home value from the solar system.
It is also worth noting that dealer fees interact with federal and state incentives. The 30 percent federal Investment Tax Credit (ITC) is calculated on the total cost of the system, and in many cases the dealer fee is included in that basis. That means a portion of the fee may be offset by the tax credit, but only if you have enough tax liability to use it. To understand how the ITC and other programs work alongside your financing, see this guide to solar incentives and rebates for homeowners, which explains eligibility and how to claim them correctly.
How to Spot Dealer Fees in a Solar Loan Quote
Dealer fees are rarely labeled as such. They hide behind terms like finance charge, origination fee, rate buydown, or simply a higher principal balance than the cash price. The fastest way to spot them is to compare the cash price of the system to the financed amount. If the financed amount is higher than the cash price, the difference is likely a dealer fee or a similar financing charge.
Ask the salesperson for three numbers in writing: the cash price, the financed amount, and the APR. If they cannot or will not provide all three, that is a red flag. A reputable installer or lender should be able to explain exactly how the loan amount was calculated and what portion of it represents financing costs.
You should also review the Truth in Lending disclosure carefully. This document is required by federal law and must show the amount financed, the finance charge, the APR, and the total of payments. If the amount financed is significantly higher than the cash price, you are paying a dealer fee. Compare that disclosure across at least three lenders before committing.
Strategies to Reduce or Avoid Dealer Fees
The good news is that dealer fees are not unavoidable. There are several proven strategies to reduce or eliminate them, and each one can save you thousands of dollars over the life of your solar system.
- Ask for a no-dealer-fee loan option. Many lenders offer both a low-rate loan with a dealer fee and a higher-rate loan with no dealer fee. Ask the installer to quote both so you can compare total costs.
- Shop independent lenders. Credit unions, local banks, and specialized solar lenders often offer competitive rates without the inflated principal that comes with dealer fees.
- Consider a home equity loan or HELOC. These are secured by your home and typically carry lower rates and no dealer fees, though they do put your home at risk if you default.
- Negotiate the cash price first. Agree on a cash price for the system, then discuss financing separately. This prevents the dealer from inflating the price to cover the fee.
- Pay cash if possible. If you have the funds, paying cash eliminates financing costs entirely and usually qualifies you for a lower system price.
Another option is to make a larger down payment. Reducing the principal balance lowers the dollar amount of the dealer fee, since the fee is typically a percentage of the financed amount. Even a 10 or 20 percent down payment can meaningfully reduce the total cost. Just make sure the down payment actually reduces the principal and is not absorbed as a separate fee.
Questions to Ask Before You Sign
Before you sign any solar loan agreement, ask the following questions and get the answers in writing. These questions will help you uncover hidden fees and compare offers on equal footing.
- What is the cash price of the system, and what is the financed amount?
- Does this loan include a dealer fee, and if so, what percentage of the system cost is it?
- What is the APR, and how does it compare to the interest rate?
- Are there any prepayment penalties or early payoff fees?
- Is the dealer fee included in the basis for the federal tax credit?
If the salesperson dodges these questions or pressures you to sign quickly, take that as a sign to slow down. A trustworthy solar professional will welcome the scrutiny and provide clear, written answers. You can also compare quotes from multiple installers through a service like SolarEnergy.ai, which connects homeowners with vetted providers and educational resources, so you can evaluate financing options side by side.
Finally, remember that dealer fees are not inherently evil. They are a legitimate financing tool, but they must be disclosed and understood. The problem is not the fee itself; it is the lack of transparency. When you know what to look for, you can decide whether a low-rate loan with a dealer fee is genuinely better for your situation than a higher-rate loan without one. In many cases, the no-fee option wins, especially if you plan to pay off the loan early or sell your home within a few years.
Take your time, run the numbers, and compare at least three financing offers before you commit. The few hours you spend reviewing loan terms can save you tens of thousands of dollars over the life of your solar system, and that is a return on investment worth pursuing.