Solar ITC 2026: What Homeowners Must Verify Beyond 30 Percent
Verify your solar ITC 2026 value beyond the 30 percent headline. Call 8337937166 to compare free quotes and protect your tax credit.
By Thomas Hayes
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
The 30 percent federal solar Investment Tax Credit (ITC) remains the single most powerful financial lever for homeowners going solar in 2026. But treating that headline number as the final word on your tax situation is one of the most common and costly mistakes in the residential solar market. The credit is real, it is generous, and it can be worth thousands of dollars. What matters just as much is everything surrounding it: your actual tax liability, the eligibility of your specific equipment, the timing of your installation, and the fine print your installer may gloss over during a sales pitch. If you are planning a solar purchase this year, the difference between a smooth five-figure tax benefit and an unwelcome surprise at filing time usually comes down to verification, not enthusiasm.
This guide walks through exactly what homeowners need to check beyond the 30 percent figure. You will learn how the credit is calculated, which costs qualify, how your tax profile shapes the real value, and which documentation you should collect before the installers leave your roof. The goal is simple: make sure the credit you were promised is the credit you can actually claim.
How the 30 Percent Solar ITC Actually Works in 2026
The federal solar ITC is a dollar-for-dollar reduction of the federal income tax you owe. It is not a rebate check, and it is not a deduction that lowers your taxable income. If your calculated credit is $9,000 and you owe $7,000 in federal income tax for the year, the credit wipes out that $7,000 liability. The remaining $2,000 generally carries forward to the next tax year, and in most residential cases it can keep carrying forward if unused. That distinction between a credit and a refund is where many homeowners first get tripped up, because a solar salesperson saying "you get 30 percent back" can sound like a cash payment when it is really a tax offset.
For systems placed in service in 2026, the residential clean energy credit stands at 30 percent of qualified expenditures, and that rate applies to both the equipment and a defined set of soft costs. The credit has no dollar cap for residential systems, which is why larger, higher-quality installations can generate a very large benefit. However, the credit is nonrefundable, meaning it cannot push your tax liability below zero. If your federal tax owed for the year is modest, you may not be able to absorb the full credit in a single filing season, even though carryforward rules usually preserve the value over time.
Here is the key takeaway before you sign anything: the 30 percent is a percentage of eligible cost, applied against eligible tax liability, subject to eligibility rules for the equipment and the homeowner. Each of those three variables deserves independent verification.
Your Tax Liability Determines the Real Value of the Credit
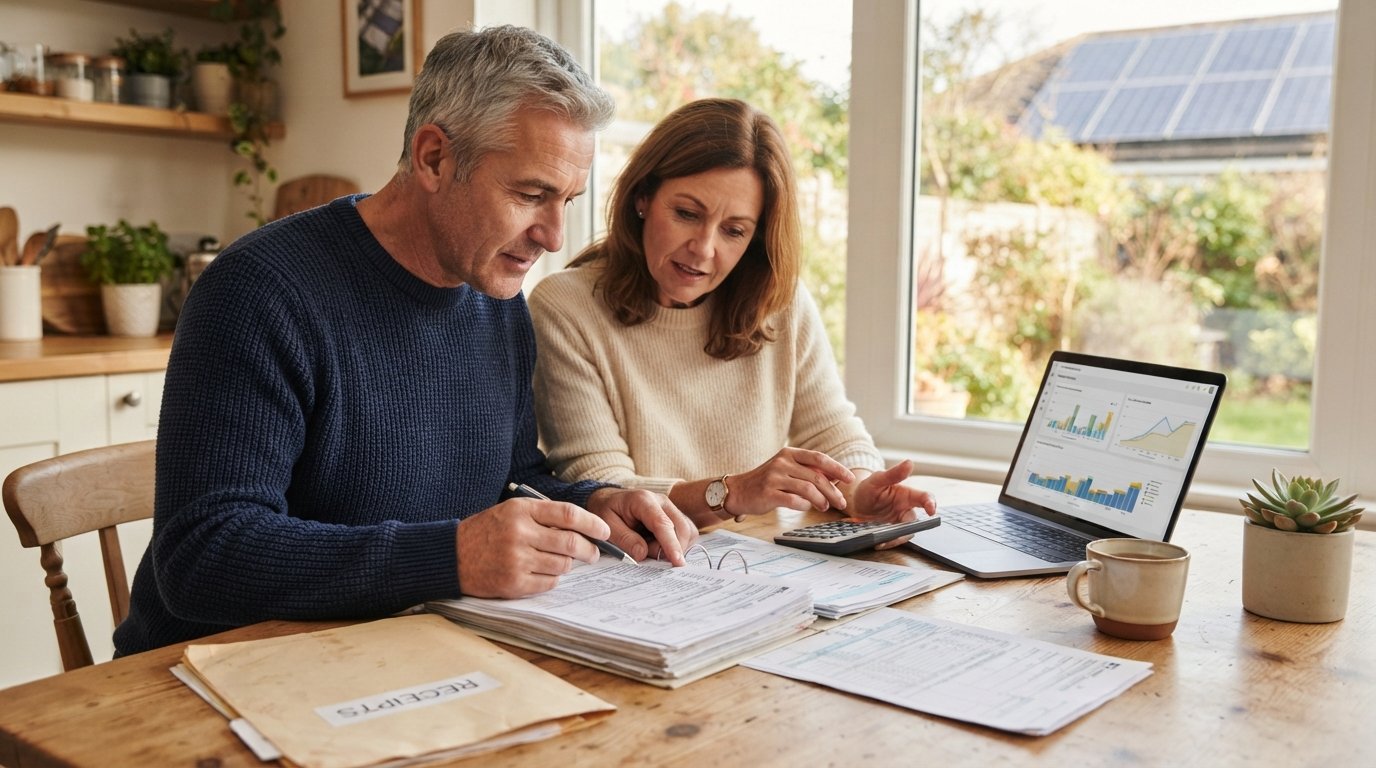
The most important number in your solar tax planning is not the system price. It is your projected federal income tax liability for the year the system is placed in service. A homeowner with a $20,000 system and a $6,000 credit who owes only $2,500 in federal tax will not see $6,000 back in that first year. They will see $2,500 of liability erased, with the balance carried forward. That is still valuable, but it changes cash flow expectations, and it can affect how you finance the system.
Several situations commonly reduce the credit you can use in year one. Retirees living primarily on Social Security may have low taxable income. Households with significant deductions, credits for children, or other tax attributes may already owe very little. Business owners with pass-through income can sometimes use the credit more aggressively, but the rules differ from the residential credit. Before you finalize a solar contract, ask a tax professional to estimate your liability for the installation year, and ask specifically how much of the projected credit you can absorb in that year and in the following years under carryforward rules.
A practical way to structure this verification is to work through a short checklist with your tax advisor:
- Estimate your total federal income tax liability for the year the system will be placed in service.
- Confirm how much of the projected 30 percent credit can be applied in that year.
- Map the carryforward schedule for any unused credit across future years.
- Identify whether any other credits or deductions might compete for the same liability.
- Document the assumptions in writing so your filing position is defensible.
That list looks simple, but completing it before installation prevents the most common "my credit was smaller than promised" complaint in the residential solar market. It also gives you a realistic payback timeline rather than a marketing one.
Which Costs Qualify and Which Do Not
The 30 percent applies to qualified expenditures, and the definition is broader than many homeowners expect but narrower than some sales presentations imply. Solar panels, mounting hardware, inverters, wiring, and labor for on-site installation generally qualify. Battery storage installed in connection with a solar system can qualify under current rules, which is a major reason storage has become more attractive. Sales taxes paid on eligible equipment often qualify. Certain permitting and inspection fees may qualify when they are part of the installation. Energy efficiency upgrades are a separate category and generally do not ride along on the solar credit.
What does not qualify is where the confusion often lives. Extended warranties, service plans, and maintenance contracts usually do not count. The cost of a new roof, even if the solar panels are mounted on it, is generally not eligible for the solar credit by itself, though the portion of the roof that functions as a mounting structure for the panels can sometimes be treated differently depending on the facts. A solar salesperson who bundles a roof replacement into the quoted "solar system price" and implies the whole thing earns 30 percent is creating risk for you at filing time. Ask for a line-item breakdown that separates eligible equipment and installation from non-eligible improvements.
If you are comparing quotes and want to understand how different estimate formats can hide or reveal these details, the guide on best solar estimate websites for 2026 homeowners explains how to read line items and spot the assumptions that affect your tax basis. Getting a transparent, itemized quote is the foundation for claiming the correct credit amount.
Timing Rules That Change Your Credit Year
The credit belongs to the tax year in which the system is placed in service, not the year you sign the contract and not necessarily the year you pay the final invoice. A system installed in late December but not energized and commissioned until January belongs to the following tax year. That timing can matter enormously if your liability is higher in one year than the next. If your installer promises a "2026 credit" but the commissioning date slips into 2027, your tax planning needs to shift accordingly. Get the placed-in-service date in writing.
Eligibility Rules Homeowners Often Overlook
The residential credit applies to your primary residence and, in many cases, a second home, but it does not apply to rental properties you do not use personally. If you install solar on a rental home, the credit generally falls under the business energy credit rules instead, which have their own requirements. If you purchase through a lease or a power purchase agreement (PPA), the third-party owner typically claims the credit and passes some benefit to you through lower payments. That is not necessarily a bad deal, but it is a fundamentally different structure, and you should not expect to claim 30 percent on your personal return.
Homeowners associations, historic districts, and local permitting rules can also affect what you are allowed to install, though they do not change federal tax eligibility. What they can change is cost, timeline, and system size, all of which feed back into the credit calculation. If you are in a state with strong additional incentives, the combined value can be substantial, but those programs have their own verification requirements and often their own application deadlines. For a broader look at how incentives and installer options fit together, resources like NewSolarQuotes provide independent educational material for homeowners comparing renewable energy options across the United States.
Documentation to Collect Before You File
Tax credits are only as strong as the paper trail behind them. The IRS does not require you to submit receipts with your return, but you must be able to substantiate the credit if questioned. Homeowners who scramble for documents in April are the ones most likely to underclaim or misclaim. Build the file as the project progresses, not after it is done.
At minimum, gather the following:
- A signed contract with a line-item breakdown of equipment, labor, and soft costs.
- Paid invoices and proof of payment for all qualified expenditures.
- The manufacturer's documentation confirming equipment specifications and eligibility.
- The final permit and inspection sign-off from your local authority.
- The placed-in-service date, documented by commissioning or utility interconnection approval.
Keep these records for at least three years after the return is filed, and longer if carryforward is involved, because the credit may be claimed across multiple tax years. If you later sell the home, the credit generally does not need to be repaid, but accurate records help with any disclosure questions and support the value proposition if you market the home as solar-equipped.
State and Utility Programs Interact With the Federal Credit
The federal credit is only one layer of the financial picture. State tax credits, rebates, SRECs, and net metering policies vary widely, and their interaction with the federal credit is not always intuitive. In general, a state rebate that reduces your basis in the system will reduce the federal credit proportionally, while a state tax credit claimed separately usually does not. Net metering, by contrast, affects your ongoing bill savings rather than your tax basis, but it heavily influences your payback period and therefore your overall return.
Because these programs change, always verify current rules with your state energy office, your utility, and a tax professional before relying on any specific number. A solar quote that projects savings based on an expired rebate or an outdated net metering rate is a quote built on sand. The verification habit you apply to the federal credit should extend to every state and local program in your proposal.
Questions to Ask Before You Sign
The single best protection against a disappointing tax outcome is a short conversation with your installer and your tax advisor before the contract is final. Ask what portion of the quoted price is eligible for the federal credit, and get the answer in writing. Ask who is responsible for documenting the placed-in-service date. Ask whether the financing structure is a purchase, a lease, or a PPA, and who claims the credit in each case. Ask how the quote accounts for state incentives and whether those incentives are capped, waitlisted, or scheduled to step down.
If the answers are vague, treat that as a signal. A reputable installer should be comfortable separating eligible from non-eligible costs and should never discourage you from consulting a tax professional. FreeSolarPowerQuotes exists precisely for this stage of the process: it is an independent educational resource and lead generation service that connects homeowners with pre-screened local solar providers for free, no-obligation quotes, without acting as an installer or utility itself. That independence matters when your goal is transparent information rather than a pressure sale.
Solar remains one of the most reliable long-term investments a homeowner can make, and the 30 percent credit is a major reason why. But the credit rewards homeowners who verify. Confirm your tax liability, confirm which costs qualify, confirm the placed-in-service date, and confirm your documentation before the system goes live. Do that, and the 30 percent becomes what it was always meant to be: a real, usable benefit rather than a number on a sales sheet.