How Solar Panels Affect Home Appraisal Value in 2026
See how solar panels affect home appraisal value in 2026, from owned vs. leased systems to documentation that protects your equity. Call (833)-793-7166 for guidance.
By Ethan Whitaker
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
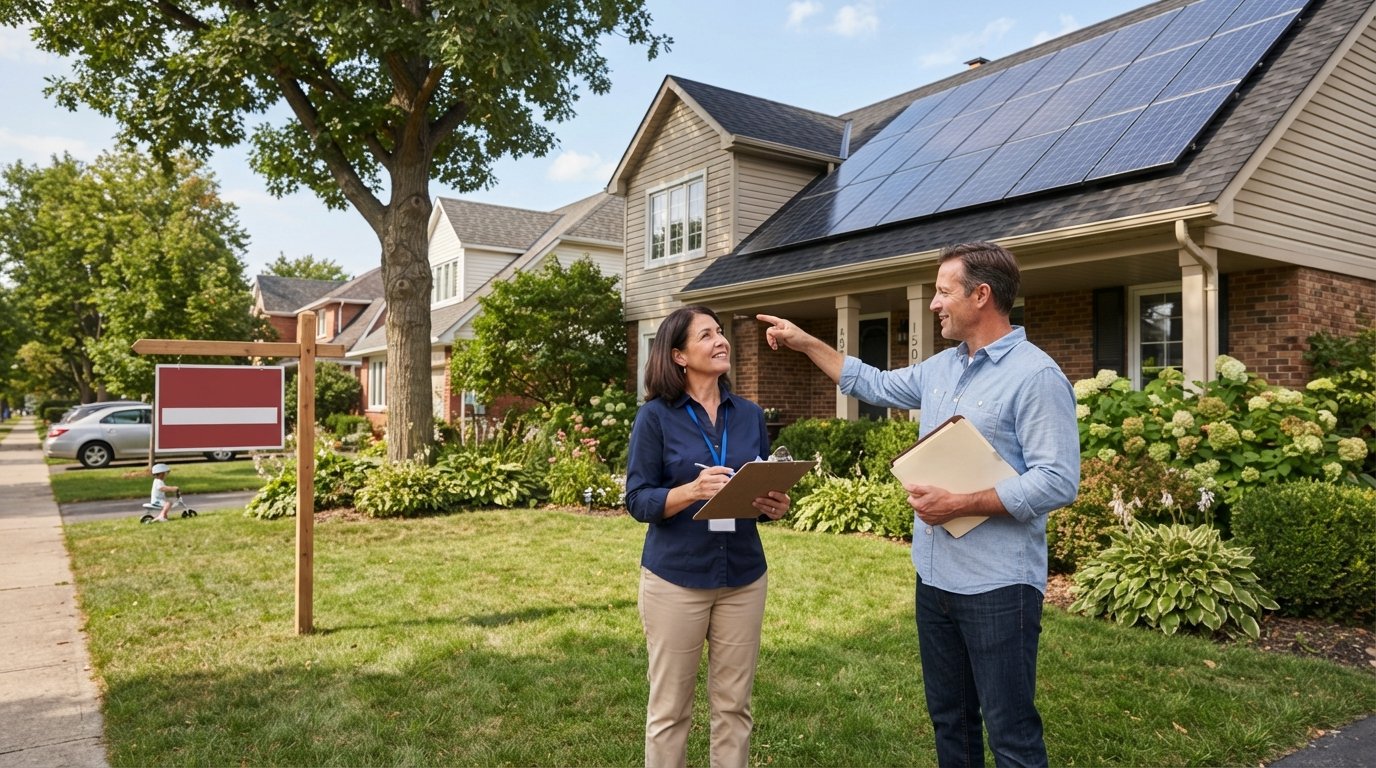
When you install solar panels, you are adding a capital improvement that can reshape your home's appraised value, but the outcome is far less automatic than most homeowners expect. Two identical solar arrays on two similar houses can produce wildly different appraisal adjustments, depending on whether the system is owned or leased, how well it is documented, and which appraiser walks through the door. In 2026, appraisal guidelines, lender overlays, and buyer expectations have matured enough that solar is no longer a novelty line item, yet it is still frequently undervalued when homeowners fail to prepare. This guide explains exactly how solar panels affect home appraisal value in 2026, from the mechanics appraisers use to the paperwork that protects your investment.
The Appraisal Mechanics: How Solar Gets Valued in 2026
Residential appraisers do not value solar panels in isolation. They value the whole property using the sales comparison approach, then make adjustments for features that differ from comparable homes. Solar enters that equation in one of three ways: as a contributory feature within the comparable sales grid, as an income-producing asset when the system is leased or under a power purchase agreement, or as a cost-based adjustment when no solar comps exist nearby. The Uniform Residential Appraisal Report now includes dedicated fields for solar system ownership and lease terms, which means the appraiser must at least acknowledge the array rather than ignore it.
The critical variable is ownership structure. An owned system, whether paid in cash or financed through a solar loan, is treated as part of the real property. The appraiser can credit its contribution to value much like a finished basement or a renovated kitchen, subject to market evidence. A leased system or PPA, by contrast, is a contractual obligation attached to the home. The appraiser must analyze the lease payment, the remaining term, and the transfer provisions, and many lenders require the lease to be disclosed and reviewed before the loan can close. In practical terms, this is the single biggest fork in the road for how solar panels affect home appraisal value in 2026.
Geography and market maturity also matter. In markets like Houston, Phoenix, and much of Florida, where solar penetration is high, appraisers have real comparable sales with owned systems and can support meaningful adjustments. In markets where solar is rare, the appraiser may lean on cost minus depreciation, which often produces a lower contributory value than the homeowner hopes for. Understanding which scenario applies to your property helps you set realistic expectations before the appraisal is ordered.
Owned vs. Leased Systems: The 2026 Appraisal Divide
Owned solar is the strongest position for appraisal purposes. When you own the panels outright, they convey with the house at sale, and the appraiser can treat them as a permanent improvement. Industry data has consistently shown that homes with owned solar sell at a premium over comparable non-solar homes, with the premium scaling roughly with system size and local electricity rates. In 2026, with electricity prices elevated across much of the country, that premium has held firm in mature markets, though it varies significantly by region and price tier.
Leased systems and PPAs present a more complicated picture. The appraiser must determine whether the lease enhances or detracts from marketability. A lease with a payment below the local utility rate can be a selling point, while a lease with escalating payments and a remaining term of 15 years can be a liability that buyers discount. Lenders increasingly require the appraiser to address the lease explicitly, and some loan programs treat the lease payment as a debt obligation in the borrower's debt-to-income calculation. The net effect is that leased solar often produces little to no positive appraisal adjustment, and in some cases it can compress the buyer pool enough to slow a sale.
If you are still in the shopping phase, this distinction should shape your financing decision. Exploring ownership structures early, including how to install your own solar panels easily with a clear ownership path, can protect your appraisal outcome years before you list the home. The general rule for 2026: owned systems build equity, leased systems build contractual complexity.
Market Data: What Solar Homes Actually Sell For
Sale price premiums for solar-equipped homes have been studied extensively, and the findings are consistent enough to cite with confidence. Research spanning multiple years and markets has found that homes with owned solar sell for a premium over comparable homes without it, with the premium often landing in the range of a few percentage points of sale price, though the exact figure swings with system size, local utility rates, and market maturity. In high-rate electricity markets, the premium tends to be larger because the avoided utility cost is more valuable to buyers.
It is important to separate sale price from appraised value. An appraiser's job is to support the contract price with evidence, not to invent a premium. If the buyer and seller agree on a price that reflects the solar value, the appraiser needs comparable sales with solar to justify it. In markets with few solar comps, the appraised value can come in below the contract price, which creates financing friction. This is why documentation and local market knowledge matter so much: the data exists, but the appraiser must be able to find it and use it.
For homeowners in Texas, Florida, Arizona, and other strong solar states, the practical takeaway is that solar value is real but not guaranteed to appear automatically in an appraisal. The premium shows up when the system is owned, documented, and supported by local comps, and it tends to be muted or absent when the system is leased or poorly documented.
Documentation: The Paperwork That Protects Your Value
The most common reason solar value gets left on the table is missing or disorganized documentation. Appraisers are generalists working under time pressure, and they cannot credit what they cannot verify. A homeowner who hands over a clean package makes the appraiser's job easy and the adjustment more likely. A homeowner who says "the panels are on the roof, the installer handled it" invites a conservative, cost-based treatment or no adjustment at all.
Prepare a solar documentation packet and have it ready before the appraiser visits. The following items cover what most appraisers and lenders need in 2026:
- System specification sheet showing panel count, wattage, inverter type, and total system size in kilowatts.
- Proof of ownership: paid invoice, bill of sale, or loan payoff statement, plus the warranty documents.
- Installation permits, final inspection sign-off, and utility interconnection approval.
- Twelve months of production data from the monitoring portal, showing actual kilowatt-hours generated.
- Utility bill history before and after installation to demonstrate real savings.
- For leased or PPA systems: the full contract, remaining term, payment schedule, and transfer terms.
Present this packet to the appraiser at the inspection and leave a copy with the lender. When the appraiser can see production data and a clean ownership record, the conversation shifts from "is there solar?" to "what is this solar worth?", which is exactly where you want it. Homeowners who plan a larger renovation alongside solar can also use a marketplace like Contractor.Homes to line up vetted local contractors for related projects, keeping the whole improvement package documented and consistent for appraisal purposes.
How Home Equity Lenders Treat Solar Improvements
Solar affects more than a purchase appraisal. If you plan to tap home equity through a cash-out refinance, home equity loan, or HELOC, the lender's treatment of your solar system matters just as much. Owned solar that is fully paid off is generally treated as part of the property's value, and the appraisal can support a higher equity position. Financed solar is treated differently: the remaining loan balance is a lien or debt obligation that reduces your usable equity, and some lenders will subtract the solar loan balance from the appraised value when calculating loan-to-value.
Leased systems and PPAs create the most friction in equity lending. Because the lease is a contractual obligation that runs with the property, lenders must review it, and some will require the lease to be subordinate to the mortgage or will reduce the appraised value to account for the obligation. In 2026, underwriting guidelines have become more standardized, but lender overlays still vary widely. The practical advice is to ask your lender how it treats solar before you apply, and to have your documentation packet ready for the equity appraisal just as you would for a sale.
It also helps to think about timing. If your solar loan has a meaningful remaining balance, paying it down before an equity application can improve your position, because the appraisal credit for owned solar is strongest when the system is unencumbered. Conversely, if you are considering a lease, understand that it may limit your future financing flexibility, not just your sale price.
Maximizing Your Solar Appraisal Outcome in 2026
The homeowners who consistently capture solar value follow a repeatable process. First, they choose ownership over leasing when their finances allow it, because owned systems are the ones appraisers can credit cleanly. Second, they keep documentation organized from day one, not the week before the appraisal. Third, they communicate with the appraiser and lender proactively, providing comps and production data rather than waiting to be asked. Fourth, they verify local incentive and net metering details with official sources, since programs change and the appraiser's market analysis depends on accurate utility context.
It also pays to understand your local market. In mature solar markets, appraisers have seen enough solar sales to support adjustments, and buyers actively look for owned systems. In emerging markets, the burden of proof falls more heavily on the homeowner. Either way, the fundamentals are the same: owned solar, clear paperwork, real production data, and a cooperative appraisal process. When those pieces are in place, solar panels can meaningfully affect home appraisal value in 2026, and the investment you made in clean energy shows up where it counts, in your home equity.